
Apartment Management Rights: How a Residential Building Earns
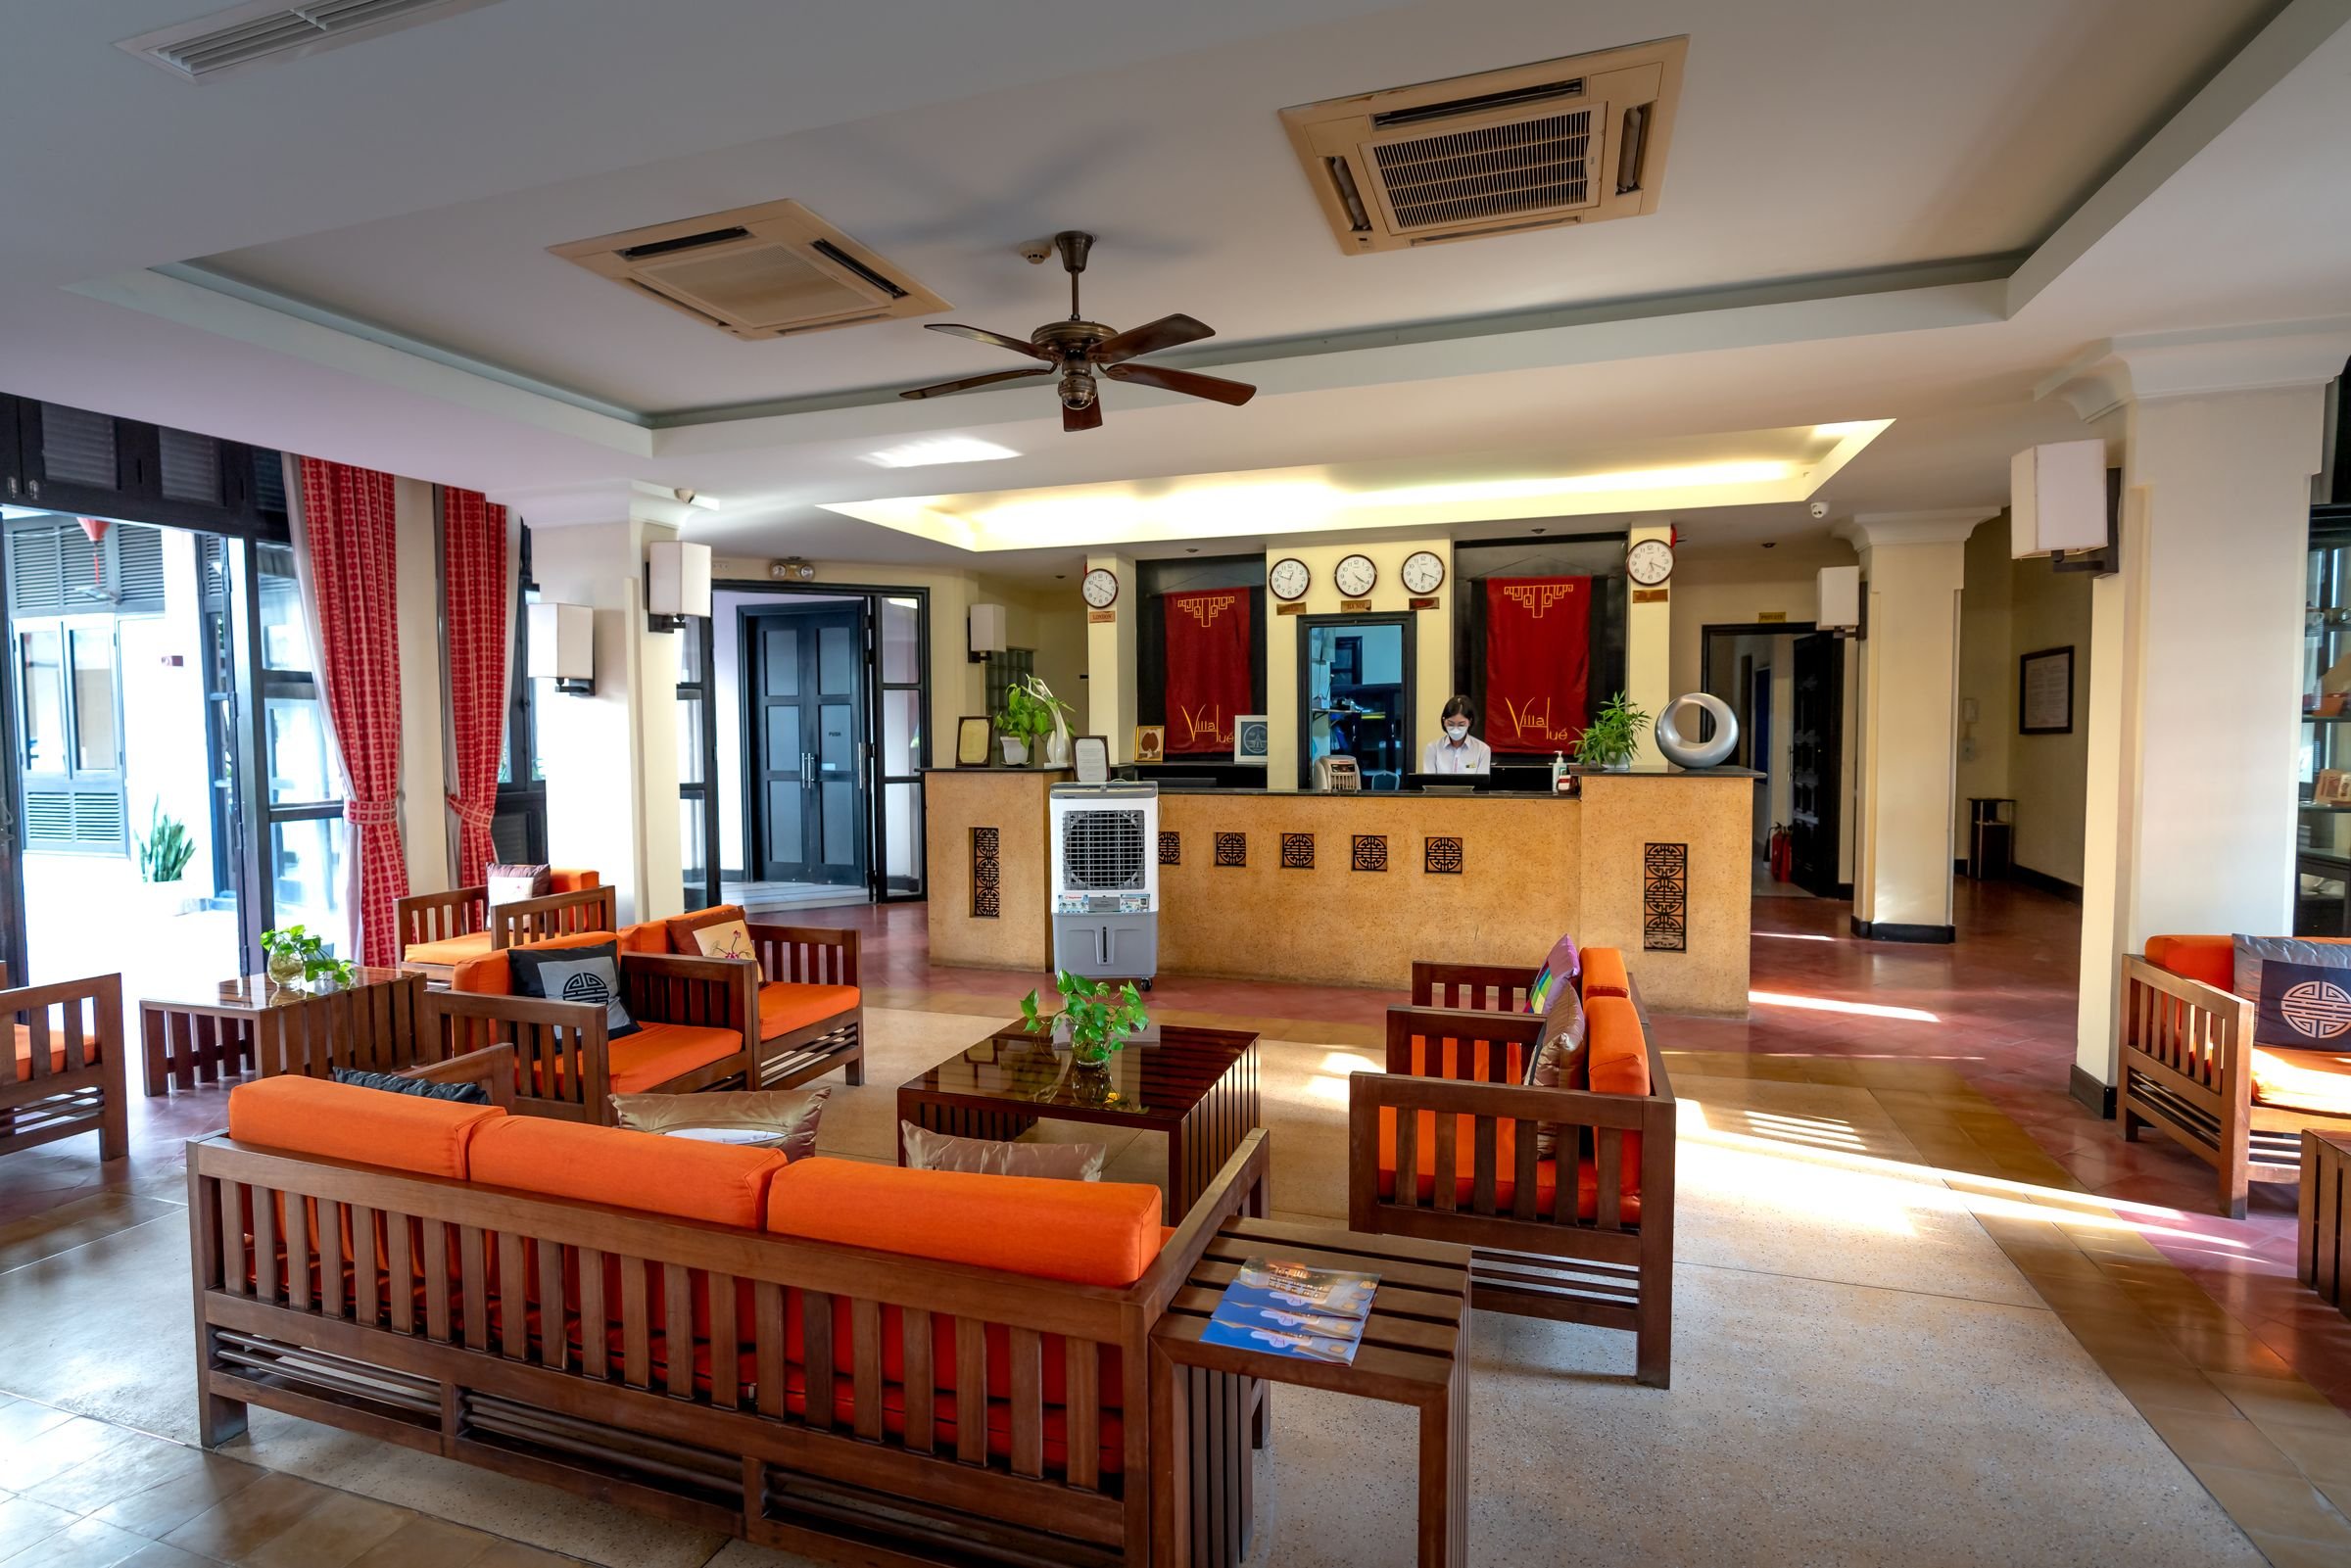
Apartment management rights in a residential building: how the letting pool works, what the manager does weekly, what lifts value and the risks.
 Accommodation Finance Hub
Apartment Management Rights · Letting Pool · Residential Buildings
Two apartment buildings can sit on the same street with the same number of lots and earn very different incomes for their onsite managers. This insight looks at the residential building itself: how the letting pool works, what the manager does each week, what lifts one building's rights above another's, and where the risks sit.
Quick Answer
Apartment management rights are a business inside a residential building: the onsite manager is paid by the body corporate to look after common property and earns letting income from the apartments whose owners join the letting pool. How many owners let through the manager, and for how long the agreements run, decides most of what the business earns and how management rights finance is assessed.
Also called: residential management rights, permanent letting management rights, unit complex management rights. Same business model in a residential building; holiday and resort complexes run differently.
What are apartment management rights?
Apartment management rights are management rights held over a residential apartment building: a caretaking agreement with the body corporate, appointments to let apartments for their owners, and usually the manager's own unit in the building, bought together as one business. The general model, and how it differs from buying a single investment apartment, is covered in what management rights are and the management rights glossary entry. This page stays on the building.
That is why apartment management rights are judged building by building. The agreements matter, but the building's mix of owners, its age and its condition decide whether the business is a going concern with steady income or a salary with a thin top-up.
How does the letting pool work in a residential apartment building?
The residential letting pool is the group of apartments whose owners have appointed the onsite manager to let them, and the manager earns letting income only from those apartments. Each investor signs their own appointment, so the pool is built owner by owner rather than handed over in one document.
- Investors in the pool. The manager finds tenants, collects rent and handles routine property management for these apartments, and earns commission and fees on each one.
- Owner occupiers outside the pool. Residents who own and live in their apartments do not generate letting income. They still benefit from the caretaking work the body corporate pays for, but with owner occupiers outside the pool the letting side of the business has fewer apartments to work with.
- Investors who use someone else. Owners are generally free to choose their own agent, so competing agents in the building can hold part of the rent roll.
The caretaking salary is paid regardless of how many owners let through the manager. The letting side moves with the pool. A building where the pool covers most investor lots gives the manager steadier income than one where the pool is a handful of apartments, which is why buyers look at pool share and lot count together rather than the lot count alone.
Questions from the owner's side, such as leaving a letting pool or buying an apartment that sits in one, belong to the serviced apartment finance guide.
Permanent or holiday letting: which apartment management rights suit you?
Permanent letting apartment management rights suit a buyer who wants steadier income and regular hours, while holiday letting suits a buyer ready to run something closer to a small accommodation business. Most residential apartment buildings are permanent letting: tenants on residential leases, rent paid weekly or monthly, and a manager who looks after leases rather than guests.
| Question | Permanent letting | Holiday letting |
|---|---|---|
| Who the guests are | Tenants on residential leases, often staying a year or more | Short stay guests booking by the night or week |
| How income arrives | Letting commission on rent collected, plus leasing and re-letting fees | Commission on room bookings, plus servicing and cleaning charges |
| Workload and hours | Regular office hours, inspections and tenant requests | Check-ins, longer days and weekend work |
| Staff needed | Often run by a couple with little or no outside staff | Usually needs cleaning and front desk staff |
| How steady the income is | Typically steady month to month while tenants stay | Moves with seasons, events and travel demand |
| How lenders view it (indicative) | Generally the more comfortable read, varies by lender | Read more cautiously because income is less predictable, varies by lender |
The rest of this page is about permanent letting, because that is what most residential buildings run. Holiday and resort complexes, where the manager runs a short stay operation, are a different business with different costs, covered in resort and hotel management rights. Other accommodation lending, from motels to holiday parks, is gathered on the Accommodation Finance Hub. How lenders size a facility across both types sits in the lender read on management rights finance.
What does an onsite manager in an apartment building do each week?
An onsite manager in an apartment building spends the week on two jobs at once: caretaking for the body corporate and property management for the owners in the pool. The onsite manager's week usually looks like this:
- Leasing and re-letting. Advertising vacant apartments, showing them, checking applicants and signing leases for owners in the pool.
- Routine inspections. Inspecting tenanted apartments on the schedule the owners and the relevant state tenancy rules require, and reporting to owners.
- Rent collection and arrears. Receipting rent, chasing late payers and following the state process when arrears run on.
- Maintenance requests. Taking tenant requests, arranging trades and getting owner approval for repairs inside apartments.
- Common property work. Cleaning, gardens, the pool, bins and minor repairs under the caretaking agreement.
- Office hours. Being available on site for tenants, owners, trades and the committee.
The letting work is what grows or shrinks the business, and the caretaking work is what keeps the body corporate on side. A manager who lets the common property slide can lose the committee's goodwill even while the rent roll looks healthy, and that goodwill matters at every renewal.
What makes one apartment building's management rights worth more than another's?
One apartment building's management rights are worth more than another's when its income is larger, steadier and more secure for longer, and that comes down to a handful of building-level drivers. The valuation method itself, and how a multiple is applied to net profit, is explained in what management rights are. What follows is what sits behind the figures.
- Pool share and lot count. A larger building with most investor lots in the pool supports more letting income. A small building, or one with a thin pool, leans heavily on the caretaking salary.
- The salary's weight in the income. Caretaking salary is typically viewed as the steadier part of net profit, but a business that is almost all salary has little room to grow.
- Term remaining. More years left on the caretaking agreement and letting authority usually means a stronger business to buy and to fund. How a lender weighs the term is covered in the lender read.
- The manager's unit. Whether the unit is well located for an office, and what it is worth on its own, affects the total deal. The unit is often funded on a commercial property loan alongside the business.
- Building age and condition. Newer buildings with sound records attract tenants and keep them. Defect history in the building can mean levies, disputes and vacancies.
- Competing agents in the building. Every apartment let by an outside agent is income the manager does not earn, and a building with several active agents is harder to grow.
Two buildings with similar profit figures can still read very differently, because one profit comes mostly from the salary and the other mostly from a deep pool. Neither is wrong, but they suit different buyers, and the goodwill being paid for is not the same. For larger complexes where pool depth starts to drive the deal, see management rights finance at scale.
What are the risks in buying apartment management rights?
The main risks in buying apartment management rights are a shrinking letting pool, competition from other agents, friction with the body corporate, problems in the building itself and changes to tenancy law. Each one hits income, and each one can be checked before you sign.
- Owners leaving the pool. Investors can sell to owner occupiers or move to another agent, and a building that loses a run of pool apartments loses letting income with them.
- Competing agents. Outside agents marketing to owners in the building can win apartments away over time.
- Body corporate disputes. A committee unhappy with caretaking standards can make renewals and approvals harder.
- Building defects. Major defects bring special levies, works on site and unhappy tenants, which can push owners to sell or switch agents.
- Tenancy law changes. State rental rules change how leases, inspections and rent increases work, and the manager's workload and costs move with them.
Due diligence on a management rights business follows the same base checklist as any business purchase. The Australian Government's guide to buying an existing business suggests reviewing three to five years of tax returns, BAS, balance sheets, profit and loss, cash flow and sales records, and verifying them independently, along with checking that leases and licences transfer. For apartment management rights, add the letting appointments for every pool apartment, the rent roll history and the defect history in the building. Lenders work from much the same set, laid out in the accommodation lender document pack.
Works
- Most investor lots sit in the residential letting pool
- Several years remain on the agreements
- Rent roll records reconcile to the trust account
- Building is sound, with no major defect history
- Committee relationship is steady and documented
Stalls
- Pool has shrunk as owners sold to residents
- Several competing agents in the building
- Profit relies almost entirely on the salary
- Open defect claims or large special levies
- Records that do not match the bank statements
A lender also checks whether the business's net profit can carry the loan, which is the serviceability test. Before you commit to a building, it is worth a broker's read on how its income will be assessed. You can check eligibility first, and the management rights guide covers the full buying process.
Apartment management rights are only as good as the building behind them. The caretaking salary gives a floor, but the residential letting pool decides how much the business can earn and grow. Pool share and lot count, the term left on the agreements, the manager's unit, the building's condition and how many outside agents are working the building all show up in the income, and lenders read them the same way.
Key takeaway: judge the building first, then the agreements, then the price, and check how a lender will read its income before you sign.Frequently Asked Questions
Apartment management rights are management rights over a residential apartment building, combining a caretaking agreement with the body corporate, appointments to let apartments for investor owners, and usually the manager's unit. The manager earns a salary for caretaking and letting income from the apartments in the pool. The management rights glossary entry covers the term in general.
Permanent management rights are management rights in a building where the manager lets apartments to long-term tenants on residential leases rather than to short stay guests. Income comes from letting commission and leasing fees plus the caretaking salary, and it is typically steadier than holiday letting. Most residential apartment buildings run this way, as the letting complex finance map sets out.
The pros and cons of apartment management rights come down to steady, salaried income and a home on site, set against long hours, reliance on the body corporate and the risk of owners leaving the pool. A building with a deep pool and years left on its agreements carries more of the upside. One with a shrinking pool or competing agents carries more of the risk, so judge the building before the price and talk to a broker about management rights finance early.
How many lots an apartment building needs for management rights to work has no fixed answer, because it depends on how many of those lots sit in the letting pool, not the total count. A smaller building with most investor lots in the pool can outperform a larger one that is mostly owner occupied. Lenders look at the income the pool produces rather than a minimum lot count, and the thresholds they use vary by lender; management rights finance at scale covers how pool depth changes the read.
When owners move into their apartments, the manager's letting income from those apartments stops, because owner occupied lots sit outside the letting pool. The caretaking salary continues, so the business shrinks rather than disappears. A run of owners moving in can weaken the income a lender relies on for serviceability, which is why pool history is checked before purchase.

 FBAA Accredited
