

One Doc Home Loan: Using One Strong FY26 Year
A one doc home loan can use one strong FY26 trading year, your latest BAS and an accountant letter to evidence self-employed income at the FY27 reset.

Non-Bank Development Funding in FY27: A Market Read
A FY27 market read on non-bank development funding: where lender standards sit, how deals are sized to GRV and a clear exit, and what it means for you.

Choosing a Non-Bank Property Lender Before CDR Lands in FY27
How to choose a non-bank property lender before the Consumer Data Right starts on 13 July 2026: compare on structure, not just the headline rate.

The FY27 Property Finance Calendar for Self-Employed Owners
The FY27 property finance calendar for self-employed owners: the staggered dates that change negative gearing, CGT, the CDR and SMSF borrowing.
Accommodation Finance: Broker or Straight to a Lender?
Broker or go direct on a motel, pub or caravan park loan? How whole-of-market access changes a specialised going-concern deal. General info only.
The One Document Behind a One Doc Home Loan
A line-by-line look at the one income document behind a One Doc home loan: what an accountant's letter or BAS must show, and how a specialist reads it.
When a Vendor Carry Is Smart, and When It Is a Trap
When a vendor carry is the smart way to close an equity gap on an accommodation deal, and when leaning on one is a trap.
Hitting a Tight Settlement Date With a Caveat Loan
A caveat loan can settle a tight accommodation purchase in days when the senior facility will not clear in time. Here is the timeline and the clean exit.
Why a Bank Knocks Back a Big Accommodation Deal
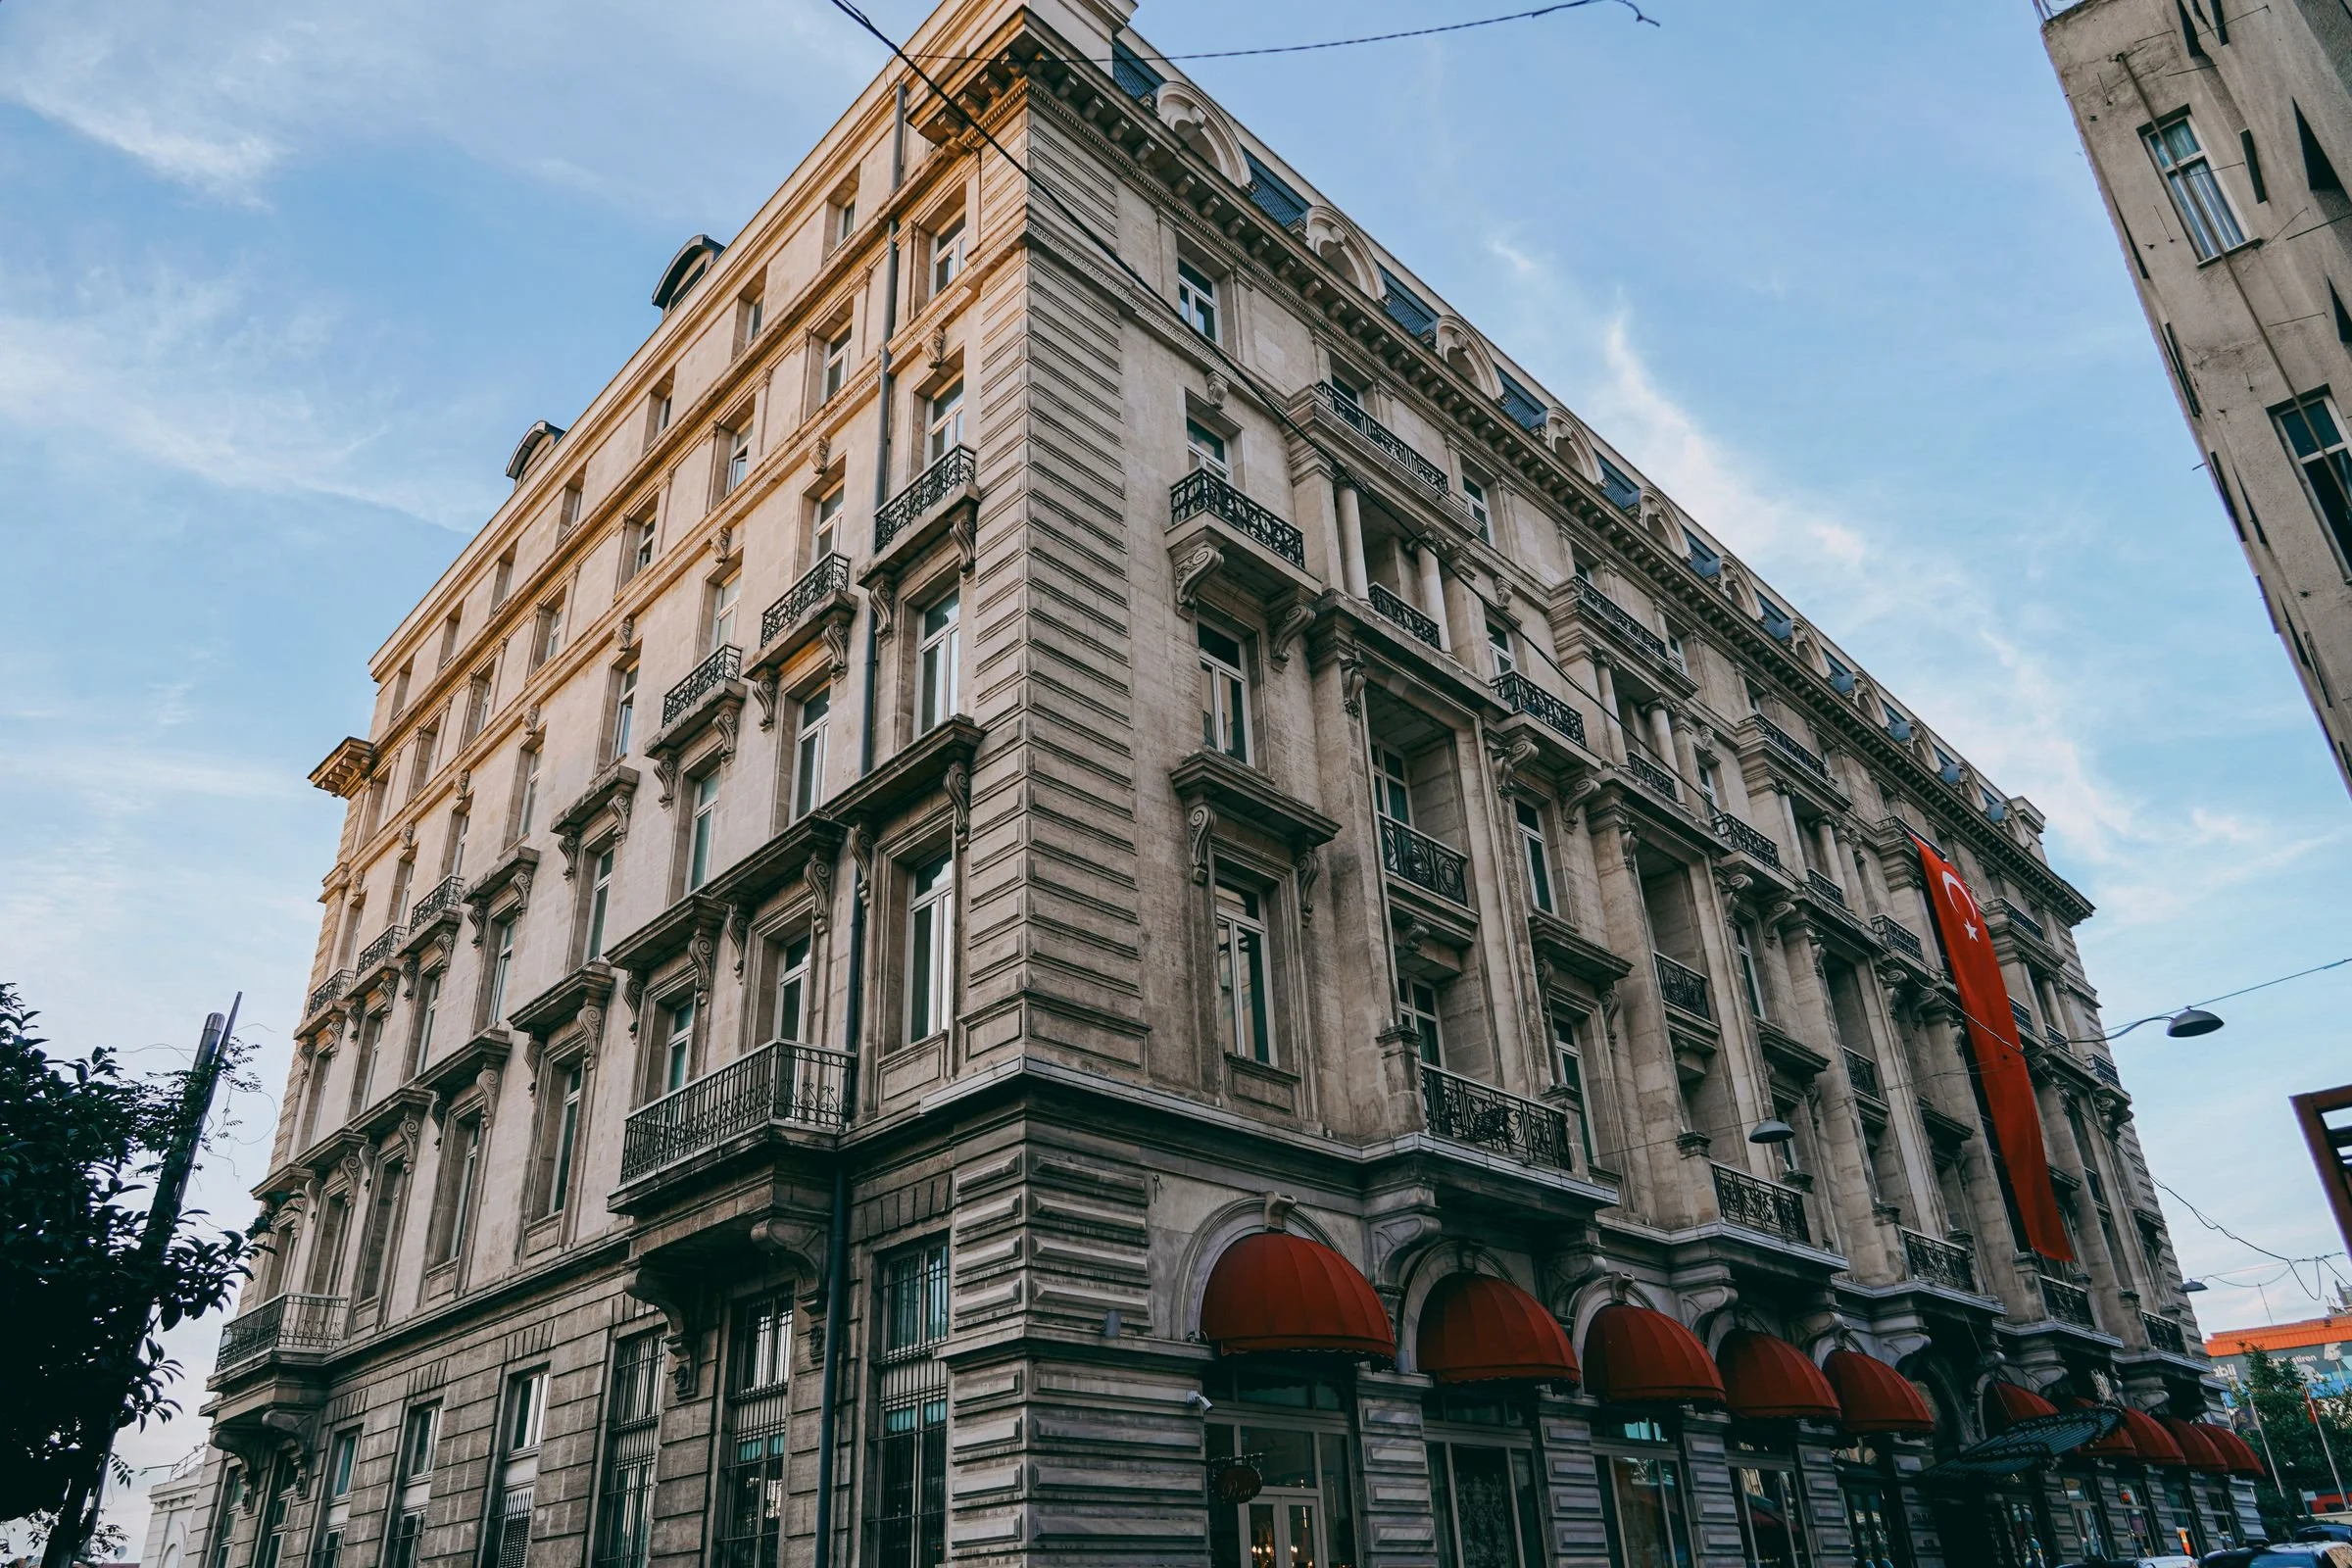
Why banks decline big accommodation deals, the four triggers behind it, and which specialist or private tier picks each one up.
Which Cafe Premises Finance Path Fits You in FY27?
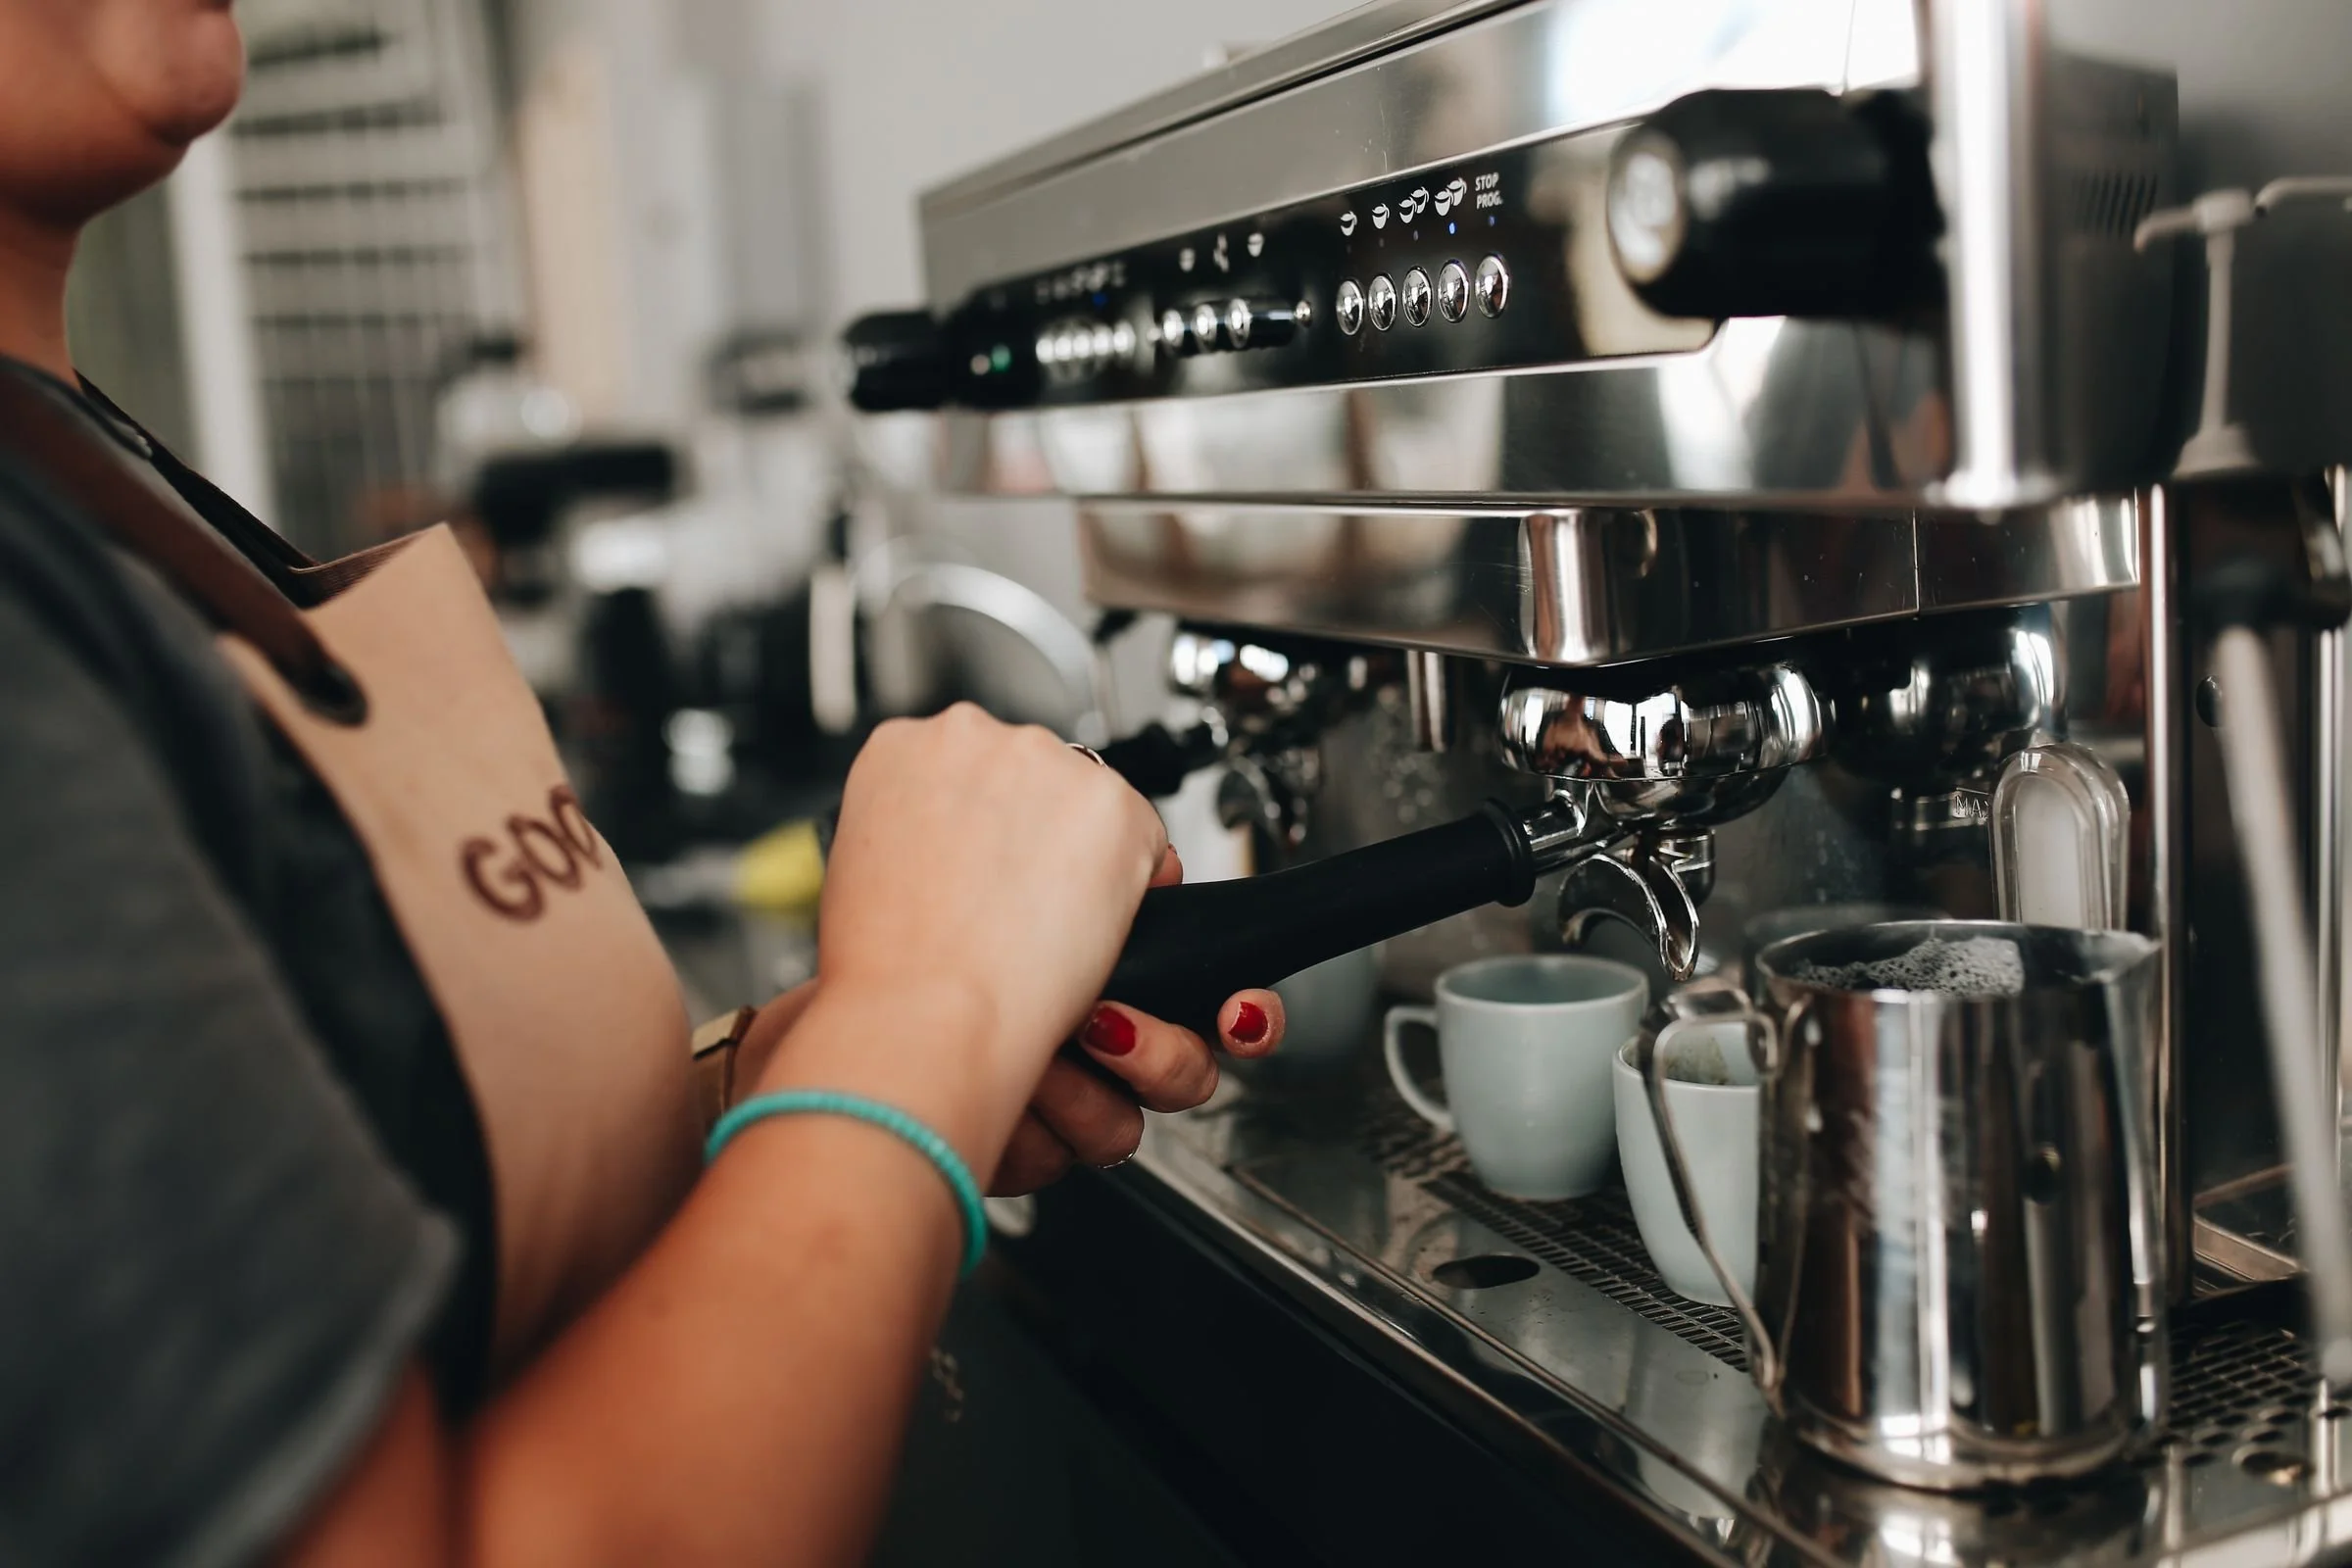
Buying cafe premises in FY27? Match your situation to the right path, owner-occupier, working capital, private lending or a One Doc home loan.